

Погляд усередину
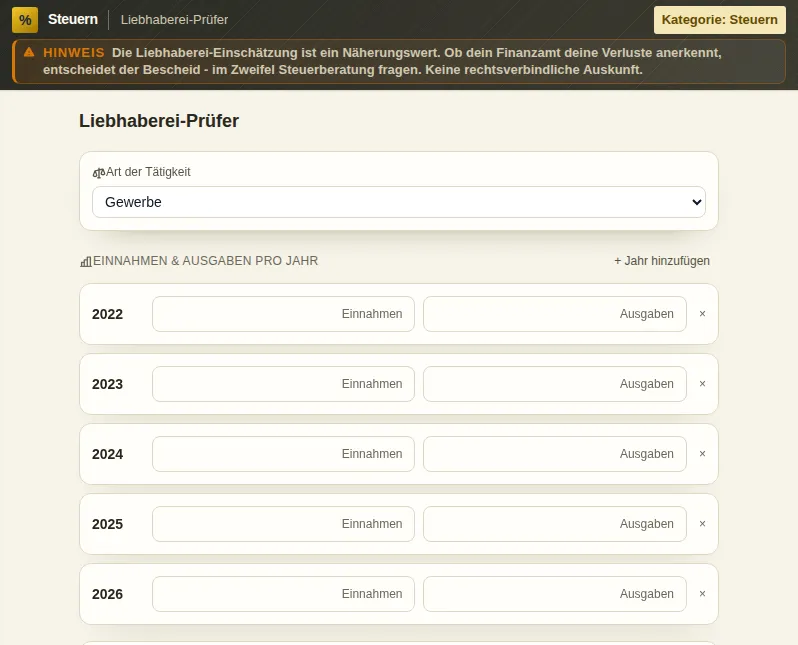
Цей безпечний перегляд показує, для чого потрібен інструмент, не виконуючи дій, що потребують акаунта.
Що вміє Хобі чи бізнес: перевірка
Liebhaberei is one of the nastiest terms in German tax law. If the tax office decides you run your activity without genuine profit intent, it stops recognizing your losses - retroactively, often over years. The classics are horse keeping, photography, the sailing boat or small-scale wine growing, but it hits any activity that writes red numbers for a long time.
The hobby-vs-business checker makes the risk tangible before the auditor knocks. You enter your results from recent years - profits and losses - and answer a few questions about your business plan, market presence, corrective measures and the nature of your activity. From that the tool computes a risk score showing where you stand between harmless and endangered.
The heart of the test is profit intent under Section 15(2) of the Income Tax Act and the question of total profit over the entire duration of the activity. A single loss year is harmless, a start-up phase too - it gets critical when no positive total profit is in sight over a long period and you simply carry on without steering against it.
This is exactly where the Federal Fiscal Court case law counts, and the checker builds it in. It is not just about numbers but about your behaviour: do you react to losses? Is there a viable business plan? Do you appear on the market like someone who wants to earn money? Or are personal inclination and leisure character so close that the losses are hobby rather than business? The checklist ticks off these criteria in turn.
The multi-year comparison presents your results as a trajectory and makes visible whether a total profit is emerging or whether the losses are structural. That is precisely the perspective the tax office takes too - not the single year but the overall picture.
Important and honest: this is a risk assessment, not a binding ruling and not tax advice. The checker does not tell you how the tax office will decide but where you sit on the scale and which levers you can pull - for example with a clean business plan or documented corrective measures that evidence profit intent.
Everything runs in your browser; your figures never leave your device. No signup, no uploaded tax secret. If the score slips into the red, that is a signal to tackle the topic seriously with a tax advisor - not only once the audit is already underway.
Функції
Risk score
A single value that places your Liebhaberei risk from harmless to endangered, built from numbers and behaviour.
Multi-year comparison
Your profits and losses as a trajectory, so a possible total profit or a structural loss becomes visible.
Profit-intent checklist
The decisive criteria under Section 15(2) to tick off - business plan, market presence, reaction to losses.
Case law built in
The test logic follows Federal Fiscal Court case law, not gut feeling.
Total profit in view
Instead of single years, total profit over the whole duration counts - exactly the tax office's perspective.
Levers instead of panic
The checker points to concrete levers you can use to evidence profit intent.
Працює в браузері
Your loss figures stay local on your device. No signup, no upload of sensitive tax data.
Як це працює
- 1
Enter your results
Enter your profits and losses from recent years. The more years, the more meaningful the trajectory.
- 2
Answer the questions
Business plan, market presence, corrective measures, nature of the activity - the answers feed into the score.
- 3
Read score and checklist
Look at the risk result and go through the profit-intent checklist point by point.
- 4
Act before the auditor comes
At high risk: gather evidence of profit intent and clarify the topic with a tax advisor.
Кому це потрібно
Поширені запитання
What does Liebhaberei mean in tax law?
Liebhaberei is an activity the tax office classifies as tax-irrelevant because no profit intent is apparent. The consequence: losses are not recognized, often retroactively. Typical examples are perpetually loss-making horse keeping, photography or boat rental.
When does an activity become Liebhaberei?
There is no fixed number of years. What matters is whether a total profit is expected over the whole duration and whether you behave like someone with profit intent. A start-up phase with losses is normal; sustained losses without steering against them get critical.
How can I evidence profit intent?
With a viable business plan, professional market presence, documented corrective measures in response to losses, and a calculation that shows black numbers in perspective. The checklist in the tool lists the relevant criteria from the case law.
Is the result a binding ruling?
No. The checker delivers a risk assessment, not a binding ruling and not tax advice. It shows you the order of magnitude of your risk and where to start - the binding clarification runs through the tax office or your advisor.
Which sections are decisive here?
Central are Section 2 on the types of income and Section 15(2) on profit intent. Added to that is the extensive Federal Fiscal Court case law that has shaped the concept of Liebhaberei over the years.
Чи зберігаються мої числа?
No. The entire assessment runs in your browser; your profit and loss figures never leave your device. No signup, no upload, no server that sees your tax data.
Схожі інструменти

Калькулятор Gewerbesteuer
Berechne die Gewerbesteuer für alle Rechtsformen (Einzelunternehmen, GbR, OHG, KG, GmbH, UG,…

Калькулятор податку на доходи
Berechne deine Einkommensteuer nach § 32a EStG. Grund- und Splittingtarif, Soli und Kirchenst…

Перевірка Kleinunternehmer
Prüfe, ob du die Kleinunternehmerregelung (§ 19 UStG) noch nutzen kannst. Mit den 2026-Grenze…

Vorsteuerabzug-Tracker
Erfasse Vorsteuer und Umsatzsteuer, berechne Zahllast pro Monat/Quartal. Rechnungsprüfung nac…

Розбір гонорарів податкового консультанта
Verstehe die Rechnung deiner Steuerberatung nach StBVV: Gegenstandswert, Zehntelsätze, Tabell…
Починаємо з Хобі чи бізнес: перевірка?
Без встановлення. Входить від Plus. Відкривається прямо в браузері.
Відкрити зараз